Selling a House During Divorce in Missouri: What to Know
The house is usually the biggest asset and the biggest fight. Here’s how to keep the sale clean.
When a marriage ends, the home carries money, memories, and a lot of emotion. That mix is exactly why selling a house during divorce goes sideways so often. Two people who don’t agree on much now have to agree on price, timing, repairs, and who signs what.
I’m Jason DeLong with Heartland Homes KC. I’ve built over 100 homes and flipped over 150 homes personally, so I know a thing or two about the process. I’ve also been a licensed Kansas City real estate agent since 2007. This guide covers how Missouri handles the marital home, how a buyout is calculated, what happens when one spouse won’t sell, and how to protect your bottom line.
If you’re in the middle of this right now and want a confidential, no-pressure conversation about your options, schedule a call with me here.
One quick note. I’m a real estate agent, not an attorney or a CPA. Use this guide to get organized, then confirm the legal and tax pieces with your own professionals.
Who Gets the House in a Divorce in Missouri?
Missouri is an equitable distribution state. A judge divides marital property in a way that is fair. Fair does not automatically mean 50/50.
Missouri is not a community property state. There’s no built-in rule that says each spouse walks away with half the house. The judge has broad discretion.
Marital Property vs. Separate Property
Under Missouri law (RSMo 452.330), property acquired during the marriage is presumed to be marital. That’s true no matter whose name is on the title.
There are exceptions. Property owned before the marriage, gifts, and inheritances to one spouse can be separate property. But it gets complicated fast.
Say you bought the house before you got married. Then marital income paid down the mortgage for ten years, or marital money paid for a new kitchen. Your spouse may have a claim to part of that value. This is where a lot of fights start, so get your attorney’s read on it early.
What Missouri Judges Consider
When dividing the home and other marital property, Missouri courts look at factors like:
Each spouse’s economic circumstances, including the desirability of awarding the family home to the spouse with custody of the children
What each spouse contributed to acquiring the property, including work as a homemaker
The value of any separate property each spouse keeps
How each spouse conducted themselves during the marriage
Custody arrangements for minor children
The bottom line is there’s no automatic winner. If kids are involved, the parent with primary custody often has an edge in keeping the home, at least for a while. But keeping the house and affording the house are two very different questions.
A Note for Kansas-Side Homeowners
The Kansas City metro sits on a state line. If your divorce is filed in Kansas, Kansas law applies, not Missouri’s. The big-picture ideas are similar, but the statutes and procedures are different. Make sure your attorney is licensed in the right state.
Your Three Main Options for the House
Almost every divorce I see lands on one of three paths.
Option 1: Sell the House and Split the Proceeds
This is often the cleanest outcome. The sale pays off the joint mortgage at closing. Both spouses are released from the loan at the same time. The net equity gets divided according to your settlement or the court’s decree.
Nobody is stuck tied to the other person’s credit. Nobody is left wondering if the ex will make the payment next month. Clean break.
Option 2: One Spouse Buys Out the Other
This works when one spouse truly wants the house and can qualify to carry it alone. That last part is the catch.
Here’s something many people don’t realize. A divorce decree does not remove a spouse from the mortgage. The lender wasn’t part of your divorce. If your name stays on the loan and your ex stops paying, your credit takes the hit.
To truly separate, the spouse keeping the house usually needs to refinance into their own name. If today’s rates are higher than your original loan rate, the payment can jump. That rate shock is why a lot of buyouts fall apart and turn into sales.
Option 3: Deferred Sale
Sometimes one spouse stays in the home with the kids until a set event, like the youngest finishing high school. Then the house is sold and the proceeds are split.
This can protect stability for the kids. But it keeps you financially tied together for years. If you go this route, spell out in writing who pays the mortgage, taxes, insurance, and major repairs. A roof replacement five years from now should not turn into round two of the divorce.
Divorce Home Buyout Calculation: How It Works
The math itself isn’t hard. The inputs are where people fight.
Step 1: Establish Fair Market Value
You need a number both sides trust. That usually means a professional appraisal, a broker price opinion, or a comparative market analysis from an agent. You can get a starting point with a free home value estimate here.
This is where my builder background matters. I walk a house the way a builder does. Roof age, HVAC, foundation, windows, and drainage all change what the house is really worth. An appraisal that misses $15,000 in deferred maintenance can tilt a buyout in one spouse’s favor.
Step 2: Subtract What’s Owed
Take the market value and subtract the mortgage balance, any home equity line, and any other liens. What’s left is your equity.
Step 3: Decide Whether to Subtract Selling Costs
This one causes more arguments than anything else. The spouse leaving often says, “No sale is happening, so don’t deduct selling costs.” The spouse staying says, “I’ll pay those costs someday, so deduct them now.”
There’s no single right answer. It’s a negotiation point, and it can swing the buyout by thousands of dollars.
Step 4: Apply the Agreed Split
Once you know the equity, apply the percentage from your settlement or decree.
A Simple Example
These numbers are hypothetical, just to show how it works:
Home value: $350,000
Mortgage balance: $210,000
Equity: $140,000
50/50 split: the departing spouse’s share is $70,000
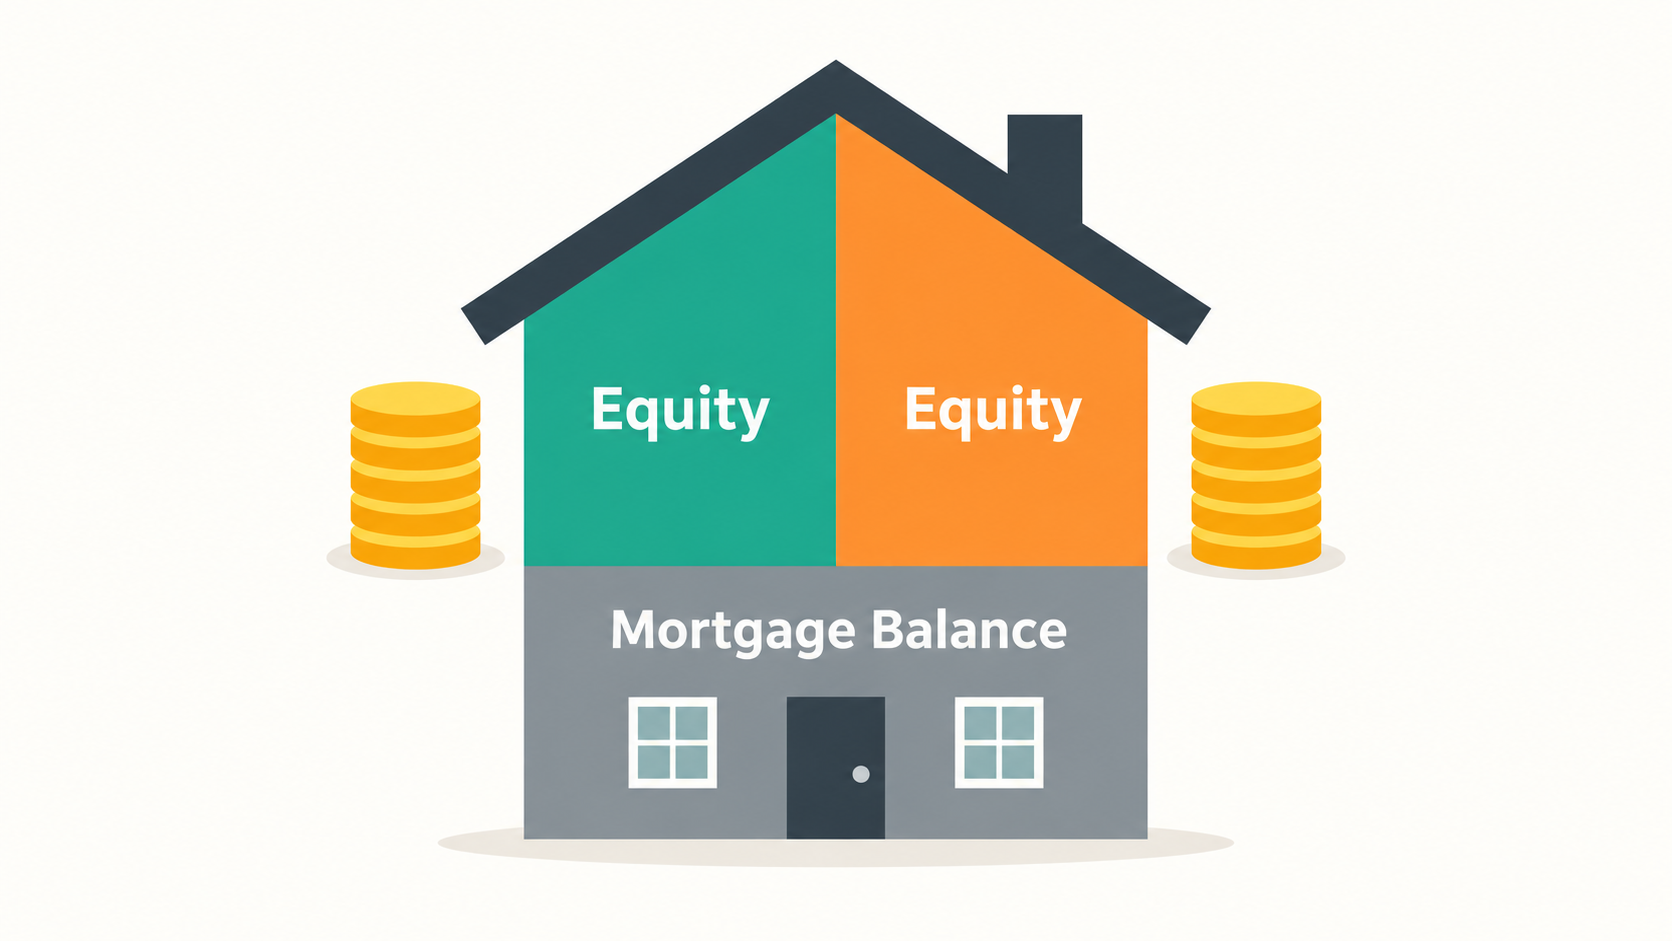
To pay that $70,000 and remove the other spouse from the loan, the staying spouse would need a new loan of roughly $280,000, plus closing costs. They also need to qualify for it on one income.
Now say both sides agree to deduct $20,000 in estimated selling costs. Equity drops to $120,000. The buyout drops to $60,000. That’s a $10,000 swing from one decision.
Some loan programs handle a divorce buyout differently from a standard cash-out refinance. Talk to a lender before you agree to keep the house.
Can One Spouse Refuse to Sell?
Short answer: yes, at least for a while.
If both spouses are on the title, both have to sign the listing agreement and the deed. One spouse can’t sell the house alone. Even when only one name is on the title, title companies will typically want both spouses to sign off on a sale of the marital home.
But refusing doesn’t last forever. A Missouri judge can order the house sold as part of the divorce when the parties can’t agree and neither can realistically keep it. Once there’s a court order, refusing to cooperate becomes a problem with the court, not just with your ex.
What Refusal Looks Like in Real Life
It’s rarely a flat “no.” It usually looks like:
Refusing to sign the listing paperwork
Blocking showings or leaving the house a mess
Rejecting every offer, no matter how reasonable
Fighting over list price for weeks
How to Prevent the Standoff
The fix is to settle the sale terms in writing before the house ever hits the market. That agreement should cover:
Who the listing agent is
The starting list price
A price reduction schedule if the house doesn’t sell
How offers get accepted (for example, any offer at or above a set number)
Who pays the mortgage and expenses until closing
Where the proceeds sit until they’re divided
I like to give sellers three pricing tiers: aggressive, market, and premium. In a divorce, agreeing on the tier upfront removes one of the biggest fights from the table.
Why the Right Divorce Real Estate Agent Matters
A divorce sale is not a normal listing. The agent you pick can calm things down or pour fuel on the fire.
Here’s what to look for in a divorce real estate agent:
True neutrality. The agent works for the sale, not for one spouse. Both people get the same information at the same time.
Everything in writing. Every update goes to both spouses, and to both attorneys if that’s what you’ve agreed.
A focus on net, not just price. A higher price with a long timeline and repair credits can net less than a clean, faster offer.
More than one option. If the only tool is a standard listing, you’ll be forced into a one-size-fits-all plan.
The Seller-First, Multi-Option Approach at Heartland Homes KC
At Heartland Homes KC, we don’t believe in one path for every seller. Divorce is a perfect example of why. Here’s what we can put on the table:
Traditional listing. Full exposure using our 100-Point Marketing Plan to drive the highest possible price.
Fix It & List It. We handle repairs and upgrades with no upfront cost to you. This is huge when neither spouse wants to put their own money into a house they’re leaving.
Cash Offers+. A market-value cash offer, a close in as little as 7 to 14 days, and in some cases the chance to keep part of the upside. If you’ve been searching for cash home buyers Kansas City sellers can trust, you can request your cash offers here.
Trade-In Program. If one spouse wants to buy their next home before the old one sells, this lets them buy first and sell later.
Even if you end up listing, a cash offer is useful. It sets a floor. When both spouses can see a guaranteed number, it’s much easier to agree on what a good listing offer looks like.
Step-by-Step: How to Keep the Sale Clean
Step 1: Talk to Your Attorney Before You List
Find out whether your court has any orders about selling or transferring property while the divorce is pending. Don’t sign a listing agreement until you know.
Step 2: Get a Neutral Valuation
Use a value both sides accept. If you can’t agree on one, each side can get their own and split the difference, or hire a single appraiser together.
Step 3: Agree on Who Pays What Until Closing
The mortgage, property taxes, insurance, utilities, and lawn care all keep coming. Decide who pays, and whether they get credited at closing.
Step 4: Put Pricing and Price Reductions in Writing
Set the list price and the reduction schedule now, while everyone is calm. Don’t leave it for the moment the house has been sitting for 30 days.
Step 5: Prep the House
If one spouse has moved out, the house can feel half-empty. Half-empty homes show poorly. Light staging, a deep clean, and a few targeted repairs pay for themselves. This is exactly where Fix It & List It helps.
Step 6: Set Communication Rules
All communication goes through the agent, in writing, to both spouses. No side conversations. No surprise decisions.
Step 7: Decide Where the Money Goes
Agree on whether the proceeds are split at closing or held by the title company until the court or your settlement directs how to divide them.
Tax Considerations When Selling During Divorce
Taxes can change the math, so loop in a CPA. A few big-picture points:
Married couples filing jointly can generally exclude up to $500,000 of gain on a primary home. Single filers can generally exclude up to $250,000. You typically need to have owned and lived in the home for two of the last five years.
Timing matters. Selling before the divorce is final, and filing jointly that year, can affect which exclusion applies.
A spouse who moved out may still be able to count the time the other spouse lived there under a divorce or separation agreement.
Transferring the house from one spouse to the other as part of the divorce is generally not a taxable event.
Your CPA should run your specific numbers before you pick a closing date.
Should You Sell Before or After the Divorce Is Final?
Selling before the divorce is final turns the house into cash. Cash is much easier to divide than a house. It also ends the shared mortgage sooner. The downside is that it requires cooperation, and sometimes court approval.
Selling after the decree means the court has already set the rules. The downside is time. Missouri requires at least 30 days from filing before a decree can be entered, and most contested cases take much longer. Every month you wait is another month of shared payments and shared risk.
There’s no universal answer. In my experience, the earlier you get a plan in place, the more options you keep.
Planning Your Next Move
Both spouses need somewhere to land. That might mean a smaller home, a rental for a while, or a fresh start in a different part of town. If you’re weighing where to go next, take a look at our guide to Kansas City neighborhoods and featured listings. It’s a good starting point for comparing some of the best neighborhoods in Kansas City for your next chapter.
Frequently Asked Questions
Do I have to sell my house if I get divorced in Missouri?
No. You can sell, one spouse can buy out the other, or you can agree to a deferred sale. If you can’t agree and neither spouse can afford to keep the home, a judge can order it sold.
How is the house split in a Missouri divorce?
Missouri uses equitable distribution. The judge divides the home and other marital property in a way that’s fair, which may or may not be 50/50. Custody, finances, contributions, and conduct all play a role.
Can I sell my house during divorce without my spouse’s permission?
Usually not. If both spouses are on the title, both must sign. Even if only one name is on the title, the other spouse’s signature is typically required for a marital home. Check for any court orders before taking action.
Who pays the mortgage during a divorce?
Whoever you agree on, or whoever the court orders. Until the loan is paid off or refinanced, both borrowers are on the hook to the lender. A missed payment hurts both credit scores.
Should we use one real estate agent or two?
One neutral agent is usually best. Two agents for one house creates confusion and more room for conflict. The key is an agent who communicates with both spouses equally and in writing.
Can a cash buyer help speed up a divorce sale?
Yes. A cash offer removes financing risk, repair negotiations, and long timelines. Even if you don’t take it, it gives both spouses a guaranteed number to measure listing offers against.
Talk to a Kansas City Real Estate Agent Who Puts Sellers First
Selling a house during divorce is hard enough. The sale itself shouldn’t add to the stress.
At Heartland Homes KC, we lay out every option side by side: listing, Fix It & List It, Cash Offers+, and Trade-In. Then you and your spouse can choose the path that maximizes your net and gets you both to a clean finish.
If you’re ready to talk through your situation confidentially, schedule a call with me today. I’ll give you straight answers and real numbers, not a sales pitch.


