How to Sell a Rental Property in Kansas City Without a Tax Shock
Depreciation recapture surprises more landlords than any other number at closing.
You bought the rental. You collected rent for years. You took the depreciation deduction every April and felt pretty smart about it. Then you sell. The settlement statement looks fine. A few weeks later your CPA calls with a number nobody warned you about.
That number is the IRS taking back part of the depreciation you claimed.
If you're figuring out how to sell a rental property in Kansas City, the tax plan matters as much as the list price. The good news is that most of the damage is predictable. A lot of it is avoidable if you plan before you sign a listing agreement or accept an offer.
I'm Jason DeLong with Heartland Homes KC. I've built over 100 homes and flipped over 150 homes personally, so I know a thing or two about the process. I own rentals myself, and I underwrite 10 to 12 deals every week. I look at a rental sale the way an investor does: what do you actually walk away with after every layer of tax?
If you want to talk through your specific property, book a quick strategy call with me here.
One quick note. I'm a Kansas City real estate agent and investor, not a CPA or tax attorney. Use this guide to get smart, then run your exact numbers with a tax pro before you sell.
The Three Taxes Hiding Inside a Rental Property Sale
When you sell a rental, the IRS doesn't see one big profit. It splits your gain into layers. Each layer gets taxed at a different rate.
Layer 1: Depreciation Recapture Tax
Every year you own a residential rental, you can deduct part of the building's cost over 27.5 years. Land doesn't count. Only the structure.
That deduction lowers your taxable rental income while you own it. It also lowers your cost basis in the property.
When you sell, the IRS "recaptures" those deductions. The portion of your gain that came from depreciation on the building is taxed at a federal rate of up to 25%. Tax pros call this unrecaptured Section 1250 gain.
Here's the part that stings. Recapture is based on depreciation that was allowed or allowable. If you never claimed depreciation, the IRS still treats your basis as if you did. Skipping the deduction doesn't save you from the recapture.
If you did a cost segregation study and depreciated items like appliances, carpet, or cabinets on a faster schedule, those pieces can be recaptured at your ordinary income rate. That rate can be much higher than 25%.
Layer 2: Capital Gains on Rental Property
The next layer is plain appreciation. That's the growth in value above what you originally paid, plus improvements.
If you held the property more than one year, that gain is taxed at long-term capital gains rates of 0%, 15%, or 20% depending on your taxable income. Most Kansas City landlords land in the 15% bracket.
If you held it one year or less, the gain is short-term. It gets taxed at your ordinary income rate. That's a flipper's problem more than a landlord's, but it's worth knowing.
Layer 3: The 3.8% Net Investment Income Tax
Higher earners pay an extra 3.8% on investment income, including rental sale gains. It kicks in when your modified adjusted gross income passes $200,000 for single filers or $250,000 for married couples filing jointly.
Those thresholds aren't indexed for inflation. A big sale year can push you over them even if your normal income sits well below.
Some real estate professionals who materially participate in their rentals may qualify for an exception. Ask your CPA if that applies to you.
A Simple Example of How the Math Works
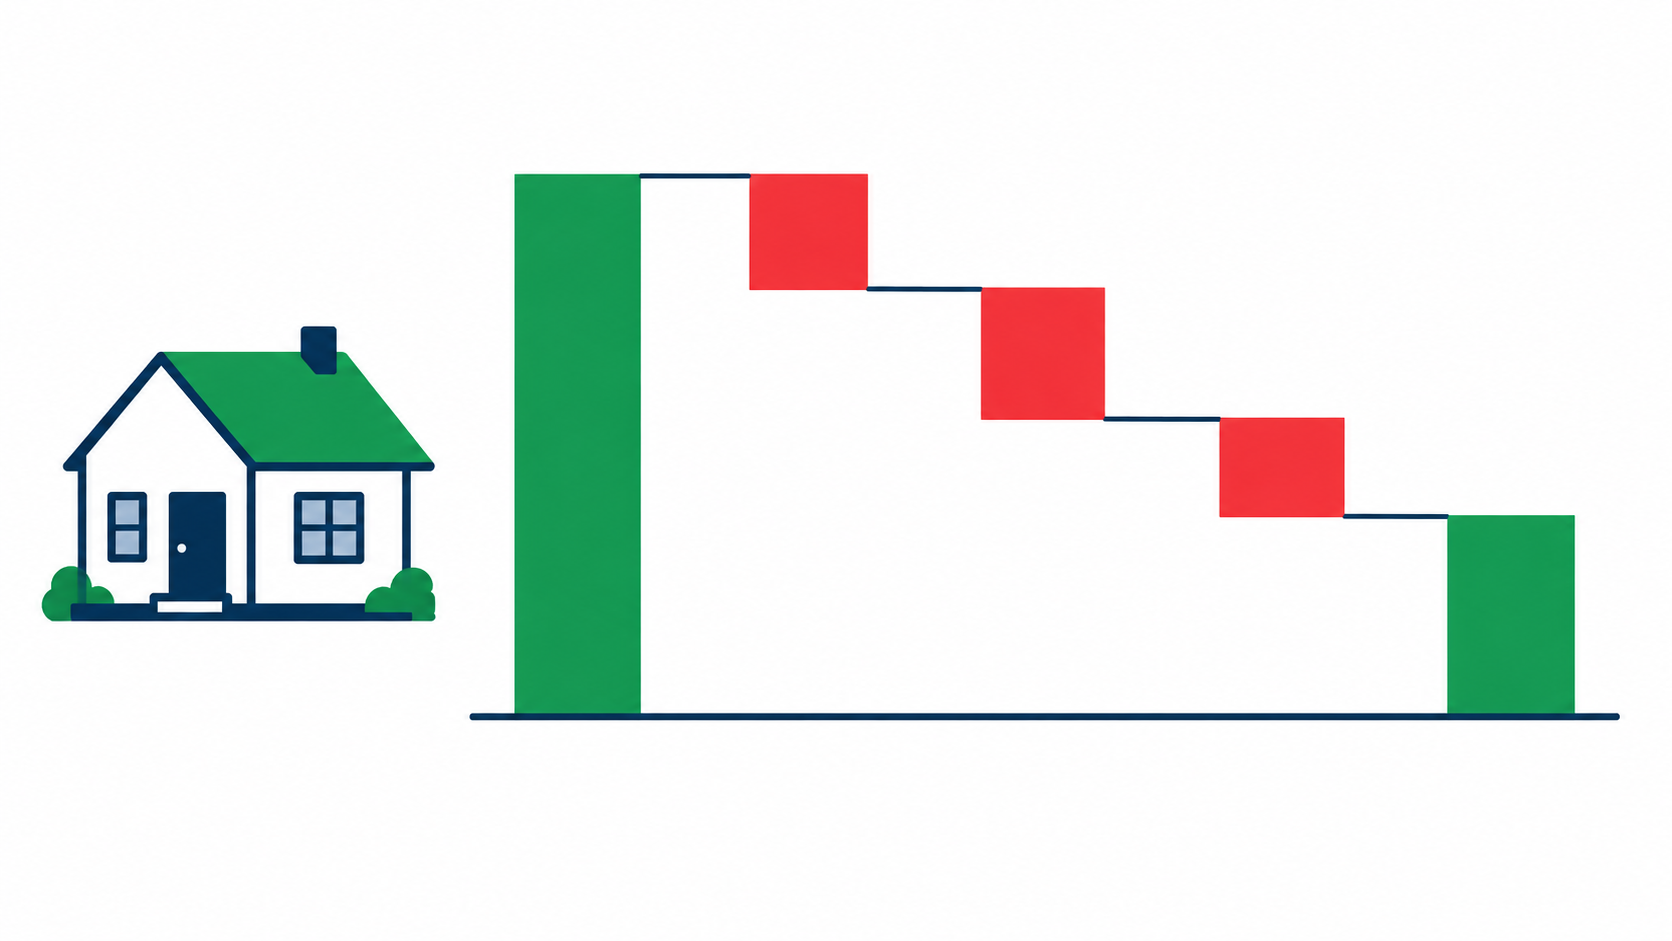
Let's walk through a hypothetical rental so the layers make sense. These numbers are for illustration only.
You bought a Kansas City rental for $200,000.
$160,000 of that was the building. $40,000 was the land.
You held it for 10 years and claimed about $5,818 per year in depreciation.
Total depreciation taken: about $58,000.
Your adjusted basis is now about $142,000.
You sell and net $300,000 after selling costs.
Your total gain is about $158,000. Here's how it breaks down:
About $58,000 is depreciation recapture, taxed at up to 25%. That's up to roughly $14,500.
About $100,000 is appreciation, taxed at 15% for most sellers. That's roughly $15,000.
If the 3.8% NIIT applies to the full gain, add roughly $6,000.
That's potentially $35,000 or more in federal tax on a property you might have thought of as a $100,000 profit. The recapture piece alone is the number that blindsides people.
This is why I always tell landlords to model net proceeds after tax, not just sale price. Maximize net, not just price.
The Kansas City Twist: Missouri vs. Kansas Taxes
Kansas City sits on a state line. Which side your rental is on, and which state you live in, can change your tax bill in a real way.
Missouri Eliminated State Tax on Capital Gains
In July 2025, Missouri signed House Bill 594 into law. Starting with the 2025 tax year, individuals can deduct 100% of capital gains reported on their federal return when calculating Missouri adjusted gross income.
That's a big deal for Missouri landlords. Missouri was the first state with a personal income tax to fully exempt individual capital gains.
There's one open question. The unrecaptured Section 1250 portion is treated as capital gain on your federal return, so many tax pros read it as covered by the Missouri deduction. Missouri hasn't published detailed guidance on that specific point yet. Confirm it with your CPA before you count on it.
If your rental sits inside Kansas City, Missouri city limits, also ask your CPA whether the city's earnings tax touches your sale.
Kansas Still Taxes Capital Gains
Kansas is a different story. Kansas taxes capital gains as ordinary income, with state rates of 5.2% to 5.58%.
That matters for Johnson County investors and anyone holding rentals in Overland Park, Olathe, Lenexa, Shawnee, or Kansas City, Kansas. Generally, Kansas can tax the gain on Kansas real estate even if you live in Missouri.
If you own rentals on both sides of State Line Road, the order you sell them in and how you structure each sale deserve real planning.
When to Sell an Investment Property (The Investor's Test)
Most landlords sell for emotional reasons. A bad tenant. A surprise roof. A busy season of life. Those reasons are real, but they aren't a strategy.
Here's the test I use. Calculate your return on equity.
Take today's realistic value. You can get an instant home value estimate here.
Subtract your loan balance and selling costs. That's your equity.
Divide your annual net cash flow by that equity.
If you have $150,000 of equity and the property nets $6,000 a year, your return on equity is 4%. That money is working harder for the tenant than it is for you.
Signs it may be time to sell or reposition:
Your return on equity has dropped well below what you could earn elsewhere.
Big-ticket items are coming due, like a roof, HVAC, sewer line, or foundation work.
The property is fully depreciated, so your annual tax shelter is gone.
You're tired of managing it and the stress is costing you more than the cash flow pays.
The neighborhood's appreciation has flattened while other Kansas City neighborhoods are climbing.
Timing can also save tax:
Hold more than one year to get long-term rates.
Selling in a lower-income year may keep you in a lower bracket or under the NIIT threshold.
Closing in early January instead of late December pushes the tax into the next year.
1031 Exchange vs Selling Outright
This is the biggest decision in any rental sale. Get it right and you can keep tens of thousands of dollars working for you.
How a 1031 Exchange Works
A 1031 exchange lets you sell an investment property and roll the gain into another investment property. You defer capital gains and depreciation recapture until you sell later without exchanging.
The key rules:
Both properties must be held for investment or business use.
A qualified intermediary has to hold the sale proceeds. If the money touches your account, the exchange can fail.
You have 45 days from closing to identify replacement properties.
You have 180 days from closing to buy the replacement.
To defer all the tax, buy equal or greater value and reinvest all the cash.
Any cash you pull out, called boot, is taxable.
Your depreciation history carries into the new property. The recapture doesn't disappear. It just moves forward with you.
When a 1031 Exchange Makes Sense
You want to stay a real estate investor.
You want to trade up from one property into a better one, or several doors into one cleaner asset.
You want to move from a high-maintenance property into a newer one in one of the best neighborhoods in Kansas City.
Your total tax bill would be large enough to justify the extra cost and deadlines.
If you're exchanging, start shopping before you list. Forty-five days goes fast. You can browse featured listings across Kansas City neighborhoods here.
When Selling Outright Wins
You're done being a landlord and want the cash.
Your gain is modest and the tax is manageable.
You're a Missouri resident selling Missouri property, and the state savings already shrank your bill.
You can't find a replacement property that pencils out. Overpaying for a replacement just to dodge taxes is a bad trade.
I see investors make that last mistake often. The tax tail should never wag the investment dog.
More Ways to Lower the Tax Bill on a Rental Sale
Document Every Capital Improvement
Improvements raise your cost basis, which lowers your gain. A new roof, HVAC system, windows, an addition, or a full kitchen remodel all count. Routine repairs usually don't.
With my architecture background, I can tell you most landlords undercount this. Pull old invoices, permits, and receipts before you sell.
Release Suspended Passive Losses
If your rental produced losses you couldn't deduct in past years, those losses may carry forward. When you sell the entire property in a taxable sale to an unrelated buyer, those suspended losses generally become deductible. That can offset a big chunk of the gain.
Consider Seller Financing
An installment sale lets you spread the gain over several tax years as you collect payments. That can keep you in lower brackets. Ordinary-income recapture on items like appliances and cost-segregated components is still taxed in the year of sale.
Convert It to Your Primary Residence
If you move in and live there for two of the five years before selling, you may qualify for part of the home sale exclusion of up to $250,000 single or $500,000 married. Depreciation after May 1997 is still taxed, and rental years before you moved in generally shrink the exclusion. This one needs careful CPA planning.
Offset With Losses Elsewhere
Capital losses from other investments can offset your gain. Some sellers plan a rental sale in the same year they clean up a losing position.
Think About Your Estate Plan
Rental property held until death generally gets a stepped-up basis for heirs. That can wipe out both the capital gain and the recapture. If you're older and the property cash flows well, holding may beat selling. Talk to an estate attorney.
How to Sell a Rental Property in Kansas City: Your Selling Options
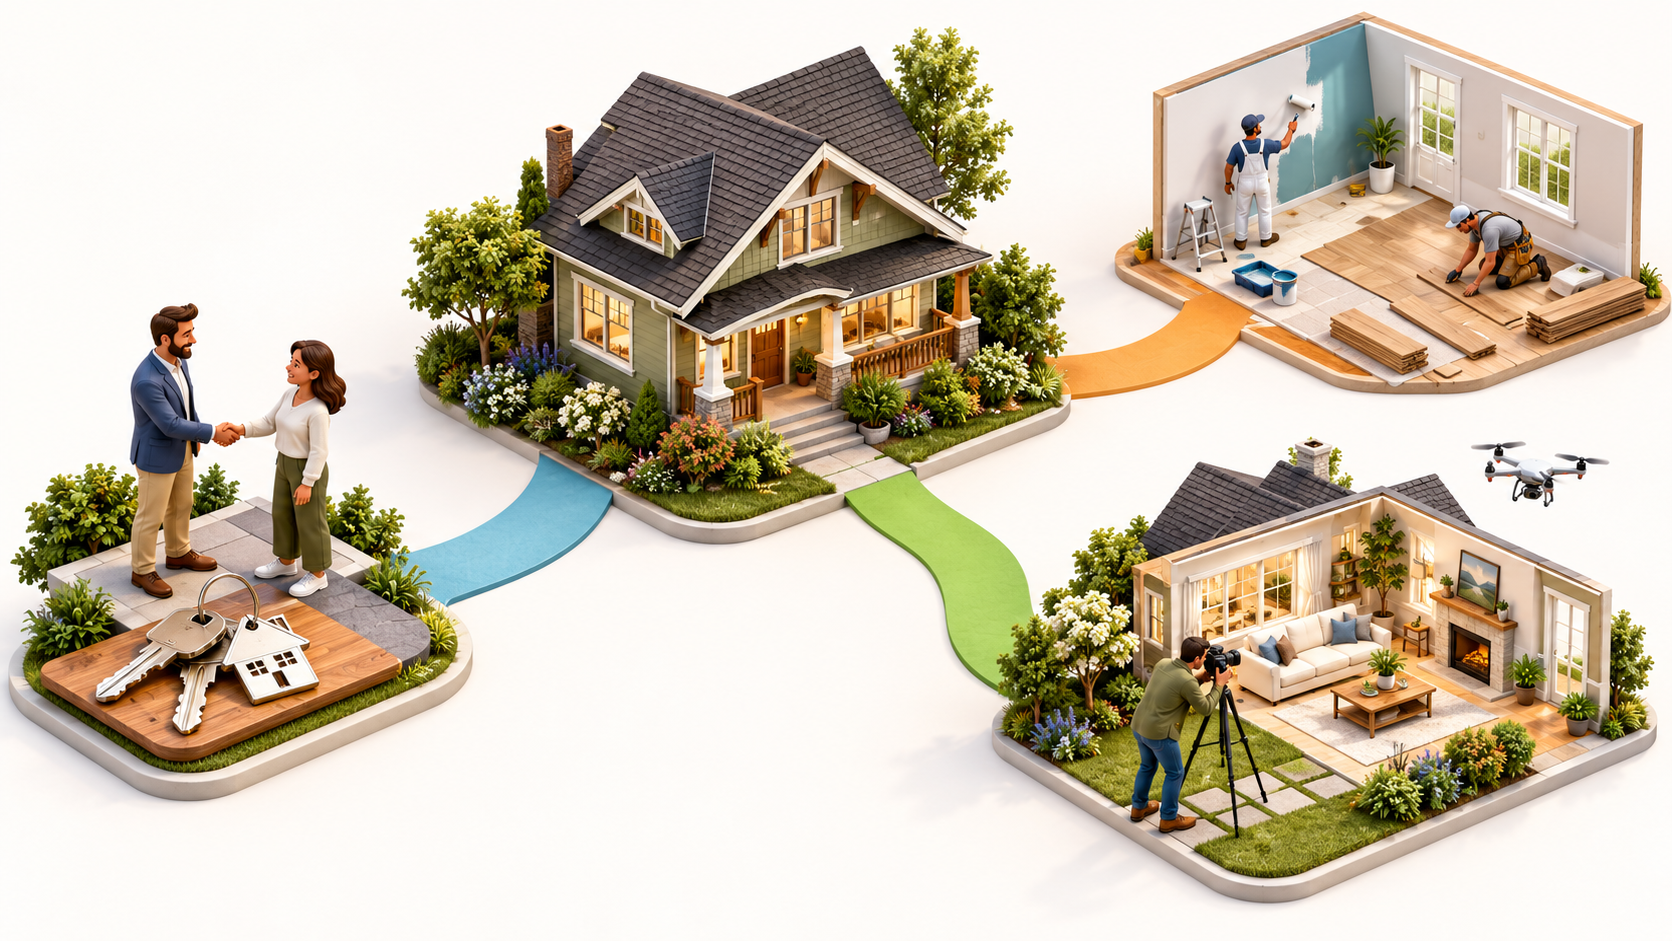
Once your tax plan is set, you need the right sale strategy. At Heartland Homes KC, we don't believe in one path for every seller. Different rentals need different exits.
Before anything else, check your lease. A tenant-occupied sale limits showings and usually narrows your buyer pool to investors. A vacant, cleaned-up rental usually sells to retail buyers for more. Know your lease terms and your local notice rules before you set a timeline.
Option 1: Cash Offers+
If the rental is tired, the tenant situation is messy, or you need speed, a cash sale may be the cleanest move. We bring you competitive offers from vetted cash home buyers in Kansas City, with closings in as little as 7 to 14 days. No repairs, no showings, no waiting on buyer financing.
Speed also helps with tax timing. If you need to close inside a specific tax year or hit a 1031 timeline, a cash close gives you control. You can request your cash offers here.
Option 2: Fix It & List It
Many rentals sell for far less than they should because of worn flooring, dated paint, and deferred maintenance. Our Fix It & List It program handles repairs and upgrades with no upfront cost to you. You get the retail buyer price without writing checks before closing.
Option 3: Full Retail Listing
If the property shows well and you want maximum exposure, a traditional listing makes sense. We market every home with our 100+ Point Marketing Plan, which includes pre-market demand building, pro photography and video, and strategic pricing tiers.
The right answer depends on your net proceeds, your tax position, and your timeline. That's why we run all three options side by side.
Your Pre-Sale Tax Checklist
Before you list, accept an offer, or call cash home buyers, gather these:
Your original closing statement from the purchase
Every depreciation schedule from your tax returns
Receipts and invoices for capital improvements
Any cost segregation study
Records of suspended passive losses
Your current mortgage payoff
A realistic value estimate
Your lease and tenant details
A decision on 1031 exchange vs selling outright
A meeting with your CPA, before you sign anything
Frequently Asked Questions
How much is depreciation recapture tax on a rental property?
Federal depreciation recapture on residential rental buildings is taxed at up to 25%. It applies to the depreciation you claimed, or could have claimed, while you owned the property. Components depreciated on faster schedules can be taxed at ordinary income rates.
Do I pay Missouri capital gains tax when I sell a rental property?
Starting with the 2025 tax year, Missouri lets individuals deduct 100% of federally reported capital gains from state taxable income. Many tax pros believe this covers the depreciation recapture portion too, but confirm with your CPA.
Do I pay Kansas capital gains tax when I sell a rental property?
Yes. Kansas taxes capital gains as ordinary income at state rates of 5.2% to 5.58%. That includes gains on Kansas rental property, generally even if you live in Missouri.
Can a 1031 exchange avoid depreciation recapture?
A 1031 exchange defers depreciation recapture and capital gains. It doesn't erase them. The deferred tax rolls into your replacement property until you sell without exchanging, or until the property passes to heirs.
Is it better to sell a rental property vacant or with tenants?
Vacant rentals usually sell for more because they appeal to retail buyers. Tenant-occupied rentals mostly attract investors who price in the lease and the risk. If the tenant is paying well below market, selling vacant often nets more.
When is the best time to sell an investment property?
The best time is when your return on equity drops, major repairs are coming due, or your goals change. Hold at least one year for long-term rates, and consider timing the closing into a lower-income tax year.
Talk Through Your Exit Strategy Before You Sign Anything
Selling a rental is one of the few moves where a little planning can save you five figures. The worst time to learn about depreciation recapture is after closing.
At Heartland Homes KC, we look at every rental sale like investors because we are investors. We'll map your options side by side: cash offer, fix and list, full retail listing, or a 1031 exchange into something better. You see the projected net on each path, then you decide.
If you're thinking about how to sell a rental property anywhere in the Kansas City metro, schedule a strategy call with Jason DeLong here. Bring your numbers. We'll bring the plan.
This article is for general education only and isn't tax, legal, or financial advice. Tax laws change, and every situation is different. Consult a qualified CPA or tax attorney before selling.


